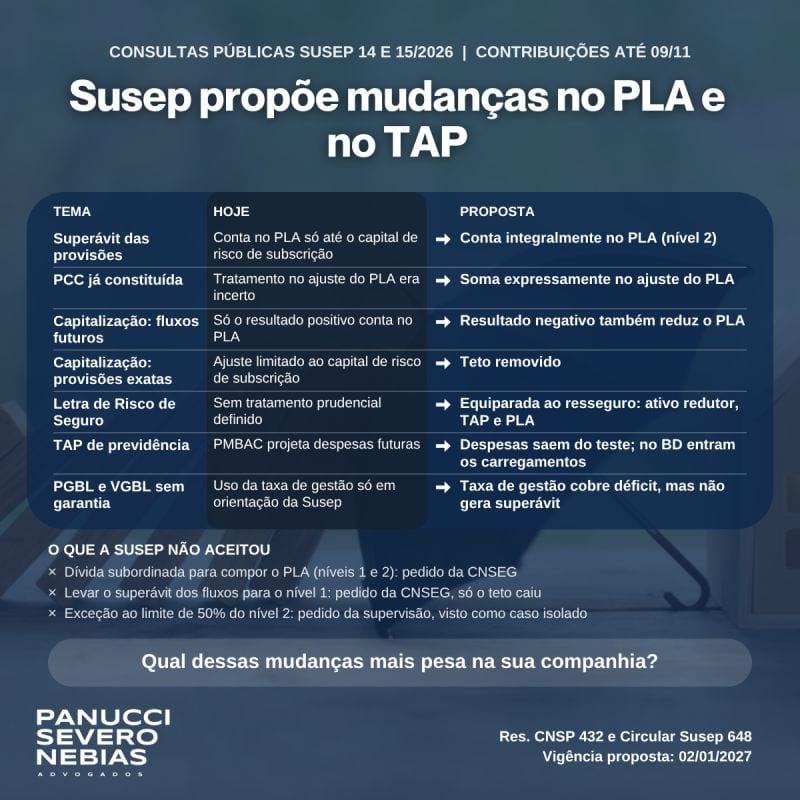
Life and pension insurers may gain regulatory capital. Capitalization companies may lose.
Susep has opened public consultations (Public Consultations 14 and 15/2026) on amendments to CNSP Resolution 432 and Susep Circular 648, the rules governing Adjusted Net Equity (PLA) and the Liability Adequacy Test (TAP). Proposed effective date: January 2, 2027.
Susep has opened public consultations (Public Consultations 14 and 15/2026) on amendments to CNSP Resolution 432 and Susep Circular 648, the rules governing Adjusted Net Equity (PLA) and the Liability Adequacy Test (TAP). Proposed effective date: January 2, 2027.
What changes
1.Surplus of provisions. Today, the excess of provisions over the realistic cash flow of registered premiums counts toward the PLA only up to the amount of underwriting risk capital. The proposal removes this cap: the surplus counts in full, but remains in tier 2.
2.PCC already recognized. It is now expressly added in the PLA adjustment, avoiding a penalty for those who recognized PCC without a deficit in the consolidated result.
3.Capitalization, unregistered cash flows. Today only the positive result counts toward the PLA. Under the proposal, a negative result also reduces the PLA; the market risk capital cap applies only to the surplus.
4.Capitalization, exact provisions versus realistic cash flow. The adjustment is no longer limited to underwriting risk capital.
5.Insurance Risk Note (LRS). For the ceding company, LRS premiums, claims and contracts follow the reinsurance or retrocession regime, depending on the risk transferred: they count as an asset that reduces the coverage requirement and are included in the TAP and in the PLA adjustments. Susep may issue its own registration and reporting criteria.
6.Pension TAP. PMBAC cash flows no longer project expenses, which are already covered by the expense provision (now calculated on a realistic basis). For defined benefit plans, loadings are now included.
7.PGBL and VGBL without guarantee. The available management fee may offset a PMBAC deficit, but does not generate a surplus. The rule, which today appears only in the TAP guidance document, moves into the regulation.
8.Terminology. "Management fee" (taxa de gestão) becomes "fee for the structuring and maintenance of pension plans and personal insurance" (taxa de estruturação e manutenção de planos de previdência e de seguros de pessoas), in line with CVM Resolution 187, with effects on the chart of accounts and the explanatory notes.
What Susep did not accept
1.Subordinated debt to make up tiers 1 and 2 of the PLA, requested by CNSEG on the grounds that it costs less than equity and aligns with Solvency II.
2.Transfer of the surplus of tier 2 cash flows to tier 1, also requested by CNSEG. Susep removed the cap but concluded that the adjustment lacks tier 1 capital quality.
3.An exception to the 50% tier 2 limit for the surplus of unregistered PPNG cash flows, suggested by the supervisory area itself. Susep analyzed data from 2023 to 2025 and treated the case as isolated.
Contributions are due by 11/09/2026 through the Susep Public Consultation System.
And at your company: which of these changes weighs most? Should Susep have accepted subordinated debt in the PLA? Tell us in the comments.