
Payment stablecoins do not only affect bank credit. They also pose new challenges to monetary policy, especially in emerging countries with fragile currencies and high inflation.
What is at stake
- When households and companies shift funds from the local currency into dollar-backed stablecoins, a form of "digital dollarization" takes place.
- This reduces the domestic monetary base, weakens the effectiveness of interest rate policy and limits central banks' ability to control liquidity and credit.
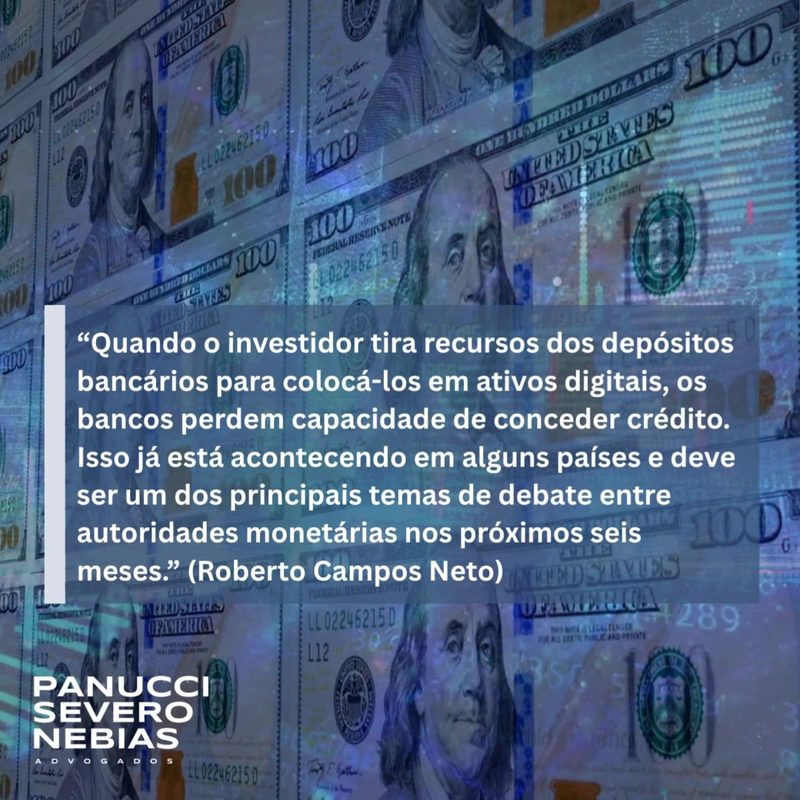
As Roberto Campos Neto warned: "When investors withdraw funds from bank deposits to place them in digital assets, banks lose the capacity to extend credit. This is already happening in some countries and should be one of the main topics of debate among monetary authorities over the next six months."
Main risks
- Loss of monetary autonomy: the larger the stock of dollar stablecoins, the lower the effectiveness of classic instruments (e.g., the Selic rate, reserve requirements).
- International transmission of shocks: changes in U.S. interest rates or liquidity come to affect, almost immediately, economies that use stablecoins as a store of value.
- Volatility in crises: in times of stress, a rush into stablecoins may intensify the outflow of funds from the local financial system.
Possible responses
- Tokenized public infrastructures (e.g., tokenized deposits in local currency), which compete in efficiency with private stablecoins but keep the credit function within the regulated perimeter.
- International coordination to define supervisory and interoperability standards.
- Clear transparency rules for stablecoin issuers, reinforcing confidence in the reserves and in governance.
In summary: stablecoins increase the efficiency of global payments, but they also reduce the effectiveness of monetary policy, especially in vulnerable economies. "Digital dollarization" raises a central question: how to preserve monetary autonomy in a world where money increasingly circulates outside central bank balance sheets.
In the next post, we will close the series by discussing prudential standards and systemic risks, including the debate on stablecoins as part of "shadow banking."


